What is the market overview and industry significance of the Clinical-Grade Wearable For Pharma And Biotech Market?
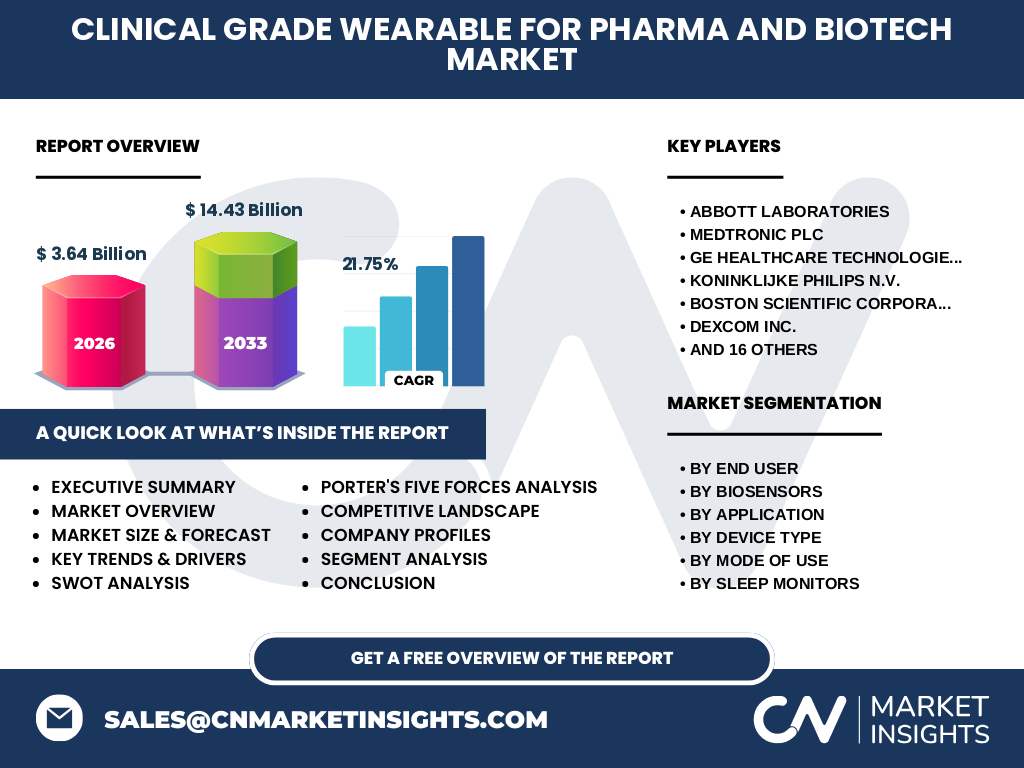
Our analysis indicates that the Clinical-Grade Wearable For Pharma And Biotech Market reached a valuation of 3.64 Billion in 2026. This sector encompasses advanced biosensors and medical-grade telemetry deployed by pharmaceutical sponsors and contract research organizations to capture continuous, high-fidelity real-world evidence. Regulatory compliance with the FDA and EMA remains paramount as developers integrate these tools into pivotal trials.
What are the structural growth drivers, restraints, challenges, and opportunities shaping this sector?
Growth is propelled by decentralized clinical trials and the demand for continuous remote patient monitoring. However, data privacy mandates such as HIPAA and GDPR present notable operational constraints. Strategic opportunities abound for firms integrating multi-parameter biosensors and wearable patch electrocardiogram monitors to capture continuous biomarkers.
Emerging trends and growth patterns in the Clinical-Grade Wearable For Pharma And Biotech Market
The shift toward hybrid monitoring models is redefining study designs. Continuous glucose monitors and sweat analysis biosensors are increasingly utilized in chronic disease management and real-world evidence generation. Innovators like Biofourmis Inc. and AliveCor Inc. are leading the charge by embedding advanced analytics into patient-facing hardware.
How did COVID-19 impact the Clinical-Grade Wearable For Pharma And Biotech Market and shape its recovery trajectory?
The pandemic acted as a major catalyst, forcing clinical researchers to adopt home-based monitoring devices to maintain trial continuity during site lockdowns. Digital biomarker collection accelerated significantly, permanently transforming regulatory acceptance of decentralized workflows and establishing a resilient post-pandemic growth trajectory.
Competitive Benchmarking: Major players, market concentration, and strategic dynamics
The landscape features a mix of medtech giants and agile innovators. Abbott Laboratories and DexCom Inc. dominate continuous glucose monitoring, while specialized players like VitalConnect Inc. and VivaLNK Inc. provide clinical-grade patch solutions. Strategic acquisitions and partnerships with contract research organizations remain the primary mechanisms for scaling proprietary analytics platforms.
Executive Summary: High-level synthesis of key findings
Driven by unprecedented technological convergence, the market is positioned for rapid expansion. Our research underscores that stakeholders prioritizing interoperable, multi-parameter biosensors will capture outsized market share as pharma companies transition away from episodic clinical assessments toward continuous telemetry.
Market forecast and projected growth trajectory from 2027 to 2033
The data suggests exceptional momentum, with the Clinical-Grade Wearable For Pharma And Biotech Market projected to surge from 3.64 Billion in 2026 to 14.43 Billion by 2033. This represents a robust compound annual growth rate of 21.75% over the forecast period.
Segmentation Analysis: Breaking down end users, biosensors, applications, and device types
Market segmentation spans multiple critical categories: End Users include pharmaceutical companies, contract research organizations, hospitals, and academic research centers. Biosensors comprise wearable patch, implantable, smart textile, sweat analysis, and multi-parameter variants. Applications cover clinical trials, remote patient monitoring, real-world evidence generation, and chronic disease management.
Regional market analysis and geographic distribution performance
North America commands the largest market share, anchored by dense clusters of biotechnology firms and favorable FDA oversight for digital health technologies. Europe follows closely, driven by stringent EMA frameworks and robust adoption across academic research centers. Meanwhile, Asia-Pacific represents the fastest-growing regional frontier due to expanding clinical trial infrastructure.
In-depth regional review of key international markets
In North America, the integration of real-world evidence into drug submissions drives high utilization of mobile cardiac telemetry devices. Across Europe, localized data sovereignty requirements mandate secure cloud infrastructures, favoring established regional suppliers like Ypsomed AG and Koninklijke Philips N.V. over foreign entrants.
Company profiles and strategic positioning of leading market participants
Industry leaders occupy distinct market niches. Medtronic plc and GE HealthCare Technologies Inc. leverage extensive hospital distribution networks, whereas pure-play innovators like Oura Health Oy and Whoop Inc. adapt consumer sleep trackers for validated clinical-grade actigraphy and polysomnography applications.
Porter's Five Forces analysis of the competitive environment
Competitive rivalry is intense, driven by rapid technological obsolescence and proprietary algorithm developments. Supplier power is moderate, balanced by specialized component manufacturers of micro-sensors. Buyer power remains high as major pharmaceutical sponsors demand customized, interoperable telemetry solutions for large-scale multinational trials.
SWOT analysis of the Clinical-Grade Wearable For Pharma And Biotech Market
Strengths include high data fidelity and continuous patient adherence. Weaknesses involve high device costs and complex data integration hurdles. Opportunities lie in emerging decentralized trials and AI-driven predictive analytics. Threats center on cybersecurity vulnerabilities and evolving international regulatory compliance standards.
Value chain analysis from raw materials to end-users
The value chain initiates with advanced semiconductor and biocompatible raw material sourcing. Manufacturers assemble these into specialized biosensors and respiratory monitors. Distributors, direct sales teams, and online channels then supply these devices to pharmaceutical companies and contract research organizations for patient deployment.
Investment insights and strategic recommendations for high-potential areas
Investors should focus on firms developing interoperable software ecosystems rather than standalone hardware. High-potential opportunities exist in multi-parameter biosensors and smart inhaler monitoring devices, which address critical compliance gaps in respiratory and chronic disease therapeutic pipelines.
Conclusion and key takeaways for industry stakeholders
The transition toward data-driven, decentralized drug development cements the necessity of clinical-grade wearables. Organizations that successfully navigate regulatory approvals and demonstrate seamless electronic health record integration will secure definitive competitive advantages through 2033.
Research methodology: How baseline estimates and market figures are triangulated
Our proprietary estimates are triangulated by combining exhaustive trade registry data, primary qualitative interviews with Chief Medical Officers and regulatory affairs experts, and secondary macroeconomic indicators. This multi-layered approach ensures precise sizing of both established and nascent segments.
Scope of the report: Coverage parameters and analytical limitations
This report covers global revenue projections from 2027 to 2033, segmenting the market by end user, biosensor type, application, device mode of use, and distribution channel. Excluded from this scope are consumer-grade wellness trackers that lack requisite medical-grade regulatory clearances for clinical trial deployment.
Recent developments: Company announcements, product launches, and strategic partnerships
Recent market activity is highlighted by strategic alliances between wearable manufacturers and major clinical research organizations. Notable product rollouts include advanced wearable patch electrocardiogram monitors and real-time continuous glucose monitoring systems designed specifically for seamless electronic data capture in decentralized trials.